Loan programs / Distressed property
Financing for the deals other lenders turn down, matched to a lender that can look past the problems.
NMLS #65972431+ years$100M+ placed
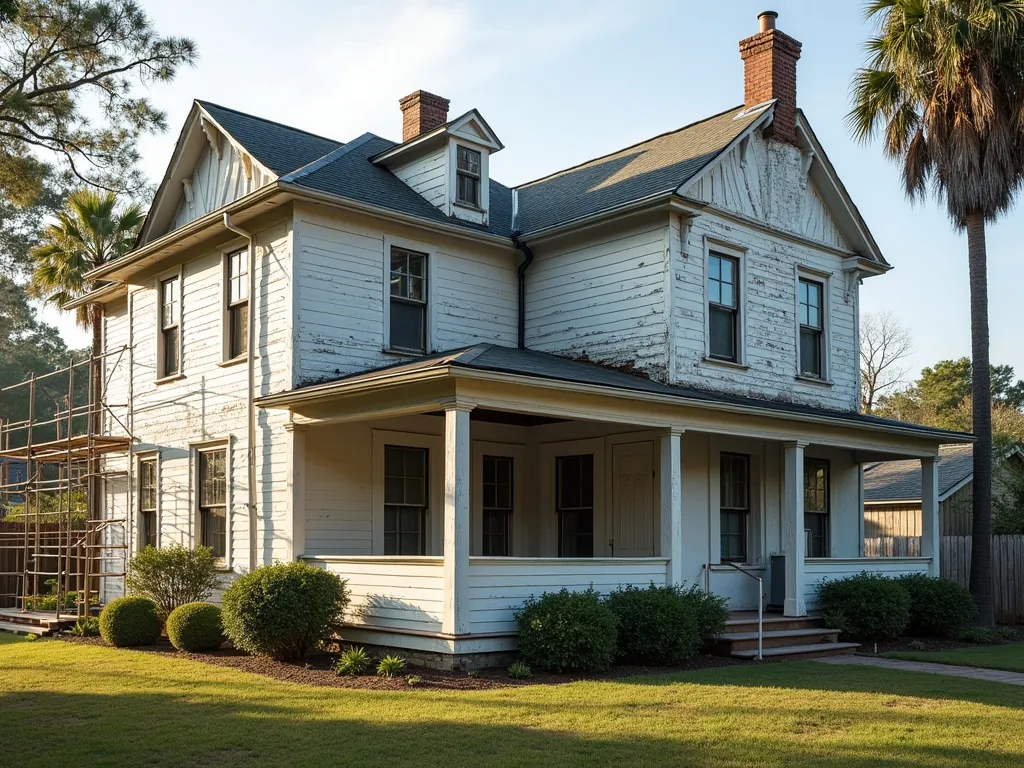
Banks walk away over condition, occupancy, title, vacancy, or unusual collateral. I look at the value, your equity, and your plan to fix the problem. You still need a sensible exit, but the review is practical, not by the book.
Properties I place loans on
Condition, value, the repair path, title, insurance, your plan, and how the asset gets sold, refinanced, or stabilized. I place mobile home and vacant lot loans today.
Loan size, term, and cost depend on the property, the equity, and the exit. Call me with the numbers and you'll know where you stand.
Address, condition, purchase price or payoff, estimated value, your plan.
Whether it works, before any paperwork.
If the first one passes, I go to the next.
Yes.
Yes. A loan needs a way to be repaid: a sale, a refinance, or stabilizing the property.
What to have in front of you
Not all of it? Call anyway. I will tell you what I need. I only do investment property.